Answer
How long do credit card payments take to settle?
Quick answer
Card payments are approved in seconds but usually take one to two business days to settle between banks, then reach your bank account on your provider's payout schedule: often one to three business days in total, longer for new accounts and over weekends. Instant payout options shorten the last step.
Updated October 2026. Evergreen page — refreshed in place as facts change.
- Authorization
- Seconds
- Funds held on the customer's card
- Batch
- Daily
- Captured sales sent at the day's cutoff
- Bank settlement
- 1–2 days
- Business days, on the networks' cycle
- Typical payout
- 1–3 days
- In total, at most providers (2026)
- Stripe new account
- 7 days
- Wait for a first US payout, Oct 2026
- Square
- Next day
- Free next-business-day transfers, Oct 2026
- Weekend sales
- Monday
- Usually settle the next business day
- Anytime Capital
- Instant sweep
- Into your business account, 24/7
A card payment is approved before the customer has put their card away, but the money takes longer to reach the business. It moves in steps: authorization, capture, batching, settlement between banks and, last, the provider's payout. This guide explains each step, how long the main providers take, why weekends add days, and what to check when a payout is late.
Payment methods on this page

What happens between a card payment and your bank account?
Approval and payment are two different events. When a card is tapped or entered, the customer's bank approves the amount and holds the funds on their card in a couple of seconds. Nothing has moved yet. The money follows later, in batches, through the card network to the acquiring bank that sponsors the business, and then from the provider to the business.
Most of the wait sits in the last two steps. Settlement between banks runs on the card networks' business-day cycle for every provider, while the payout depends on the provider's schedule and on the rail it uses to send the money.
| Step | What happens | Typical time |
|---|---|---|
| Authorization | The customer's bank approves the payment and holds the funds | Seconds |
| Capture | The business confirms the final amount: at once for most sales, on shipment for some online orders | Immediately, or when the order ships |
| Batching and clearing | The processor sends the day's captured payments to the card networks at a daily cutoff | End of the day |
| Settlement | The networks move the money from the customers' banks to the acquiring bank, less interchange | Usually one to two business days |
| Payout | The provider pays the business, less its fees, on its payout schedule | Next business day to several days; instant options exist |
Where the money is, step by step
- 1
Approved
Held on the customer's card; nothing has moved yet.
Customer's bank - 2
Captured
Confirmed for settlement, still at the customer's bank.
Customer's bank - 3
Cleared
Sent to the card network in the day's batch.
In transit - 4
Settled
At the acquiring bank, less interchange.
Provider balance - 5
Paid out
Swept into your business account, or sent to your bank.
Your account
How long does each provider take to pay out?
Settlement between banks takes roughly the same time whichever provider you use. What differs is the last leg: most providers pay out on a schedule over ACH, so the money waits for the next payout run and then for the bank transfer itself. New accounts and businesses the provider rates as higher risk usually wait longer.
Faster options shorten that leg for a percentage of the amount. On $5,000 of weekly sales, Stripe's 1.5% Instant Payout fee is $75 a week and Square's 1.95% instant transfer fee is $97.50, or $3,900 and $5,070 a year (published US fees, October 2026).
| Provider | Standard payout | Faster option |
|---|---|---|
| Stripe | A 2-day schedule for many lower-risk US businesses (up to 14 days for higher-risk ones), after a 7-day wait for a new account's first payout | Instant Payouts, usually within 30 minutes, for 1.5% of the payout (50¢ minimum) |
| Square | Free next-business-day transfers to your bank | Instant transfers for 1.95% of the amount, up to $10,000 |
| Shopify Payments | A US minimum of 3 business days, with Friday-to-Sunday sales combined into one payout | Payouts to Shopify Balance in as little as 1 business day; no instant payout to an outside bank |
| PayPal | Sales land in your PayPal balance, then transfer to your bank | No separate instant transfer rate published for business accounts |
| Clover | Standard deposit timing not published on the pages we reviewed | Rapid Deposit, 24/7, for 1.75% per transfer, up to $10,000 per request |
| Anytime Capital | Settled sales sweep instantly into your Anytime Capital business account, nights and weekends included | From the account: RTP or FedNow to other US banks in seconds, same-day wire or ACH |
From settled sale to your account, by provider
- Anytime CapitalInstant sweep, 24/7
- Stripe Instant~30 minutes, 1.5% fee
- SquareNext business day
- Stripe standard2 business days
- Shopify Payments3+ business days
- Stripe first payout7 days
Why do weekends and holidays delay payouts?
Card networks settle between banks on business days, and most payouts travel over ACH, which also settles only on business days. Card sales made from Friday evening to Sunday usually settle on Monday, and an ACH payout of them often arrives on Monday or Tuesday. A federal holiday adds another day. That is why payout schedules are written in business days, not calendar days.
Instant payment rails work differently. RTP, run by The Clearing House since 2017, and the Federal Reserve's FedNow, launched in 2023, settle in seconds around the clock, every day of the year. A payout sent over them, or a balance that sweeps into a business account on the same platform, takes the weekend out of the last leg, although card settlement itself still follows the networks' business-day cycle.
A Friday-night card sale, across the week
Taking card sales
Every day
Friday-night sale
Waits for Monday
Card settlement
Business days
ACH payout
Business days
Instant sweep
Anytime Capital
Why is my payout taking longer than usual?
When a payout is later than the schedule says, the cause is usually on a short list. Most clear on their own, or once you answer the provider's questions.
Telling your provider about a big launch or an unusually large order before it happens is the simplest way to avoid a hold. Our guide to merchant accounts covers reserves and holds in more depth.
- A new account: many providers hold the first payout for several days while they confirm the business
- A risk review, triggered by a sudden jump in volume, an unusually large payment or a change in what you sell
- Refunds and chargebacks, which are taken out of the payout and can pause it if they exceed your balance
- A reserve, where part of each day's sales is held back for a set period
- Payments not yet captured, such as online orders charged only when they ship
- A new or mistyped bank account, which providers often verify before paying out to it
- Weekends and bank holidays falling between settlement and payout
Do debit cards, American Express and ACH payments settle at different speeds?
With an all-in-one provider, debit and credit card sales follow the same payout schedule, and American Express usually does too. Businesses with their own merchant account can see differences, for example where American Express settles under a separate agreement, so check the terms for each card brand.
Bank payments are slower. An ACH debit is submitted in batches and typically takes one to three business days to settle, and a provider may wait longer before treating it as final, because the customer's bank can return it. Same-day ACH shortens that where it is offered. Our ACH vs credit card guide compares the two in full.
How do you reconcile payouts with your sales?
Match each payout to the provider's payout report, never to a day's sales total. A payout is gross sales less processing fees, refunds, chargebacks and dispute fees and any reserve, and it can cover more than one day of sales, especially after a weekend. The worked example below shows why a $5,000 week arrives as less than $5,000.
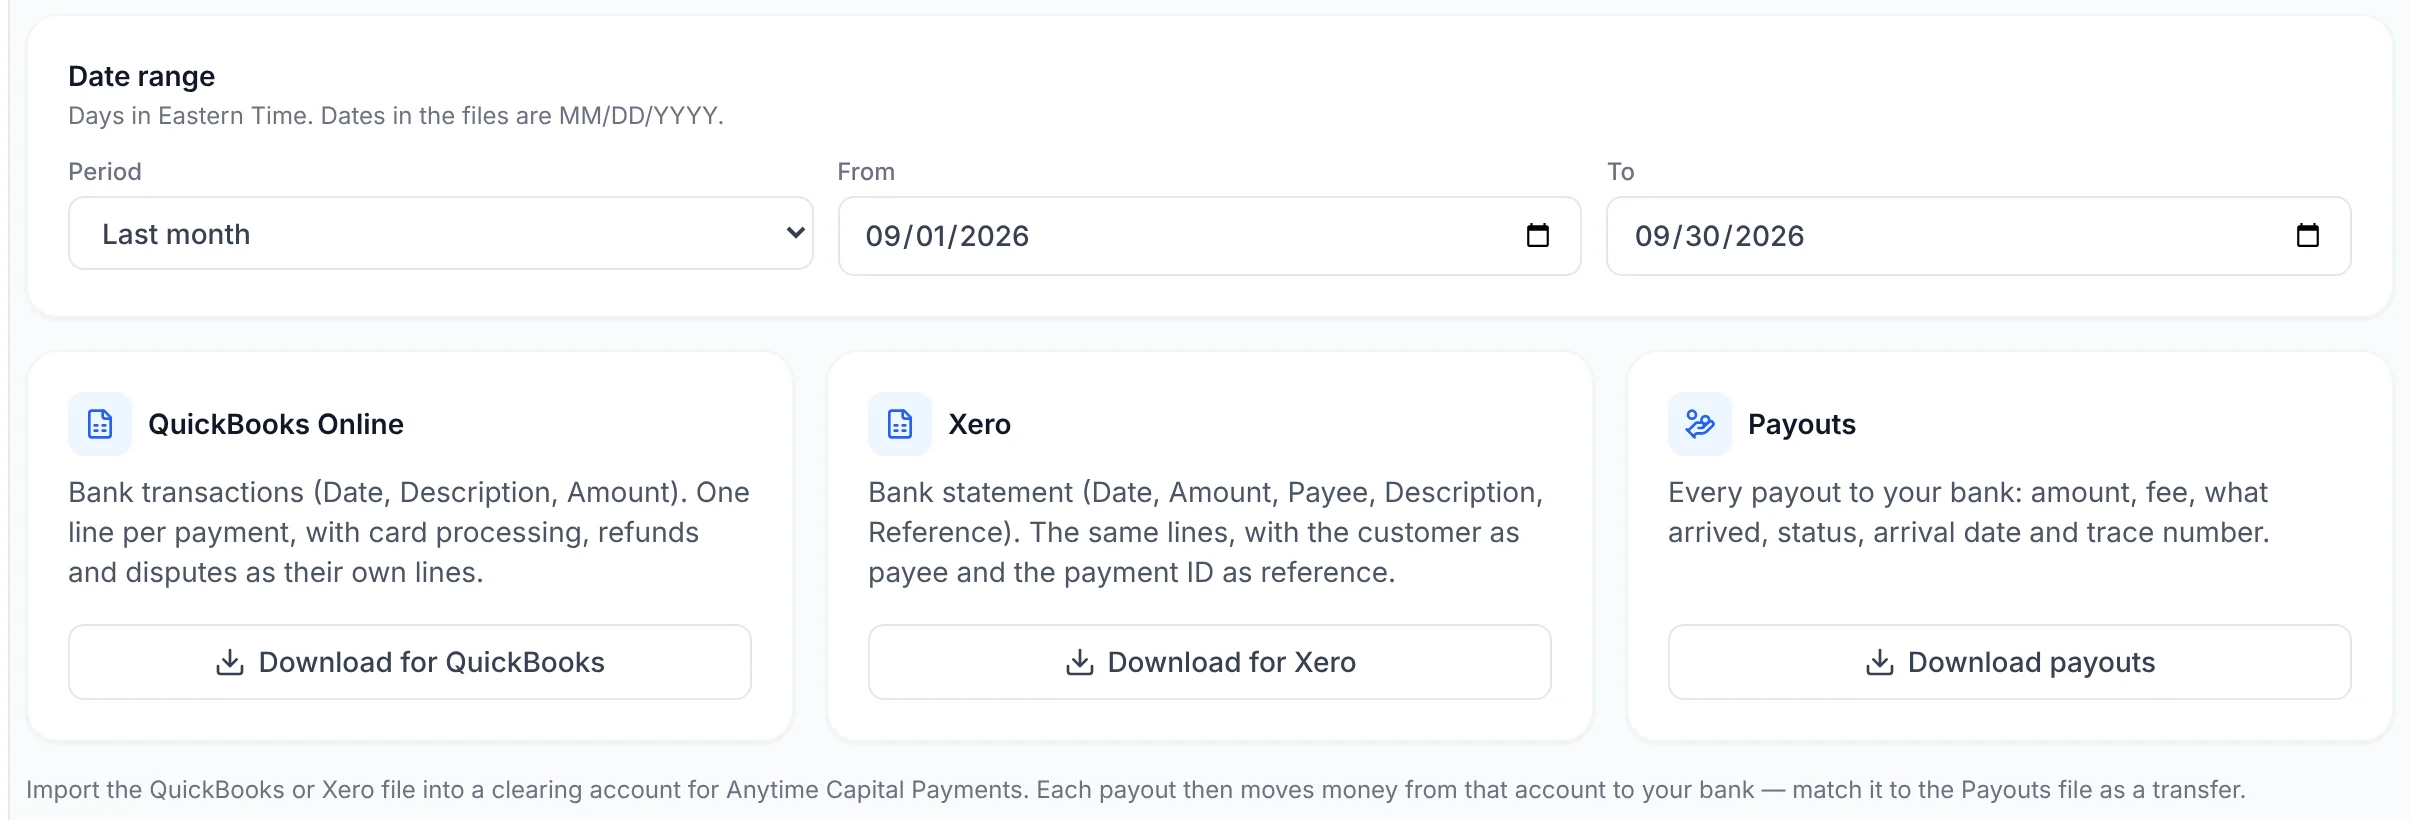
In accounting software, the clean way to do it is a clearing account for the provider. Record each sale, fee, refund and dispute in it from the provider's export, and record each payout as a transfer from the clearing account to your bank. When the clearing account's balance matches what the provider says it is still holding, the books are right.
| Line | Amount |
|---|---|
| Gross card sales: 50 sales of $100 | $5,000.00 |
| Processing fees at 2.9% + 30¢ | −$160.00 |
| One refund | −$100.00 |
| One $80 chargeback, plus a $15 dispute fee | −$95.00 |
| Payout | $4,645.00 |
How Anytime Capital pays out card sales
Anytime Capital Payments takes the payout leg out of the timeline. Your payments balance and your Anytime Capital business account sit on the same platform, so settled sales sweep into the account instantly, nights and weekends included, where they are already spendable on employee cards.
From there, money goes out by RTP or FedNow to other US banks in seconds, same-day wire, ACH, local rails in 71+ countries or same-day USDC and USDT transfers. Businesses processing $1M+ a year can agree custom payout schedules and reserve terms with a named account manager. Card settlement between banks still follows the networks' cycle; what disappears is the wait for a payout run and a bank transfer.
Processing is subject to compliance review, as it is at any regulated payments provider, and a new account's first payments may be reviewed before they are released. Our processing times page shows how each payment method behaves on Anytime Capital, and the dashboard shows each payout's expected arrival before you confirm it.
On Anytime Capital
FedNow, RTP, Fedwire and ACH in one business account
Pick the rail per payment instead of per bank: instant when it has to land now, a wire when the counterparty insists, ACH when it can wait, and local rails or stablecoins when it crosses a border. Sign up online in minutes.
- RTP & FedNowSeconds, any day
- WireSame day
- ACH to vendorsSame day or next day
- 71+ countriesMinutes to same day
- USDC & USDTMinutes, including weekends
Business account
Send and receive on every US rail
US account and routing numbers in your business's own name. Get paid by FedNow, RTP, wire or ACH, and pay the same ways, with every movement in one ledger.
Enterprise treasury
Operating accounts, approvals, API
Operating accounts and sub-accounts, approval rules and an audit trail, plus an API and signed webhooks for moving money from your own systems.
Personal
A cash account with a debit card
A cash account and card with early direct deposit and crypto built in, opened online in minutes, with no minimum balance.
Frequently Asked Questions
Do credit card payments settle on weekends?
Card networks settle between banks on business days, so sales from Friday evening to Sunday usually settle on Monday, and ACH payouts also wait for a business day. Instant rails such as RTP and FedNow run every day, so money already settled can move over them on a weekend.
What is the difference between authorization and settlement?
Authorization is the customer's bank approving the payment and holding the funds, which takes seconds. Settlement is the money actually moving from the customer's bank to the business's acquiring bank, which happens in batches, usually one to two business days later.
How long does a refund take to reach the customer?
The business usually issues a refund at once, but the customer's bank typically takes several business days to post it, often five to ten, depending on the card issuer. A refund made before the original payment settles may simply cancel the pending charge.
How long does a business have to capture a card payment?
It depends on the card network and the kind of business, but an authorization that is never captured usually expires within days for most online payments, and the hold drops off the customer's card. Businesses that charge on shipment should capture as soon as the order goes out.
Are instant payouts worth the fee?
They can be when cash is tight, but a percentage on every transfer adds up: moving $5,000 a week at Square's published 1.95% instant transfer fee is $97.50 a week, or $5,070 a year (October 2026). Planning around the standard schedule avoids the charge.
Why doesn't my payout match my sales?
Payouts are usually net: the provider deducts its fees, refunds, chargebacks and any reserve before sending the money. Reconcile each deposit against the provider's payout report, which lists the payments it includes, rather than against gross sales.
Does the payment amount affect how fast it settles?
Not by itself, but a payment far larger than your usual sales can trigger a risk review that delays the payout. If you expect a large order, tell your provider before it comes in.
What is a batch in card processing?
A batch is the group of card payments sent for settlement together, usually all of a day's captured payments at a daily cutoff. All-in-one providers close batches automatically. With some terminals and merchant accounts the business closes its own batch at the end of the day, and a batch left open settles late, which pushes back the payout.
Keep reading
Important Disclosures
- Third-party fees and product details cited on this page are each company's published US pricing, or industry-typical ranges, as of the date shown and may have changed. Check current pricing with the provider before you decide.
- Information on this page is general and educational — it is not financial, legal, or tax advice.
- Anytime Capital is a fintech company, not a bank. Payment processing, banking and payout services are provided by Anytime Capital's licensed partners. Rates shown are for US card payments; international cards, currency conversion and disputes may carry additional fees shown in your dashboard before you accept a payment.
- Anytime Capital is a fintech company, not a bank. Banking services are provided by our licensed banking partners. Stablecoins and other digital assets are not bank deposits, are not FDIC-insured and may lose value.